
Introduction
For FY 2025-26 (AY 2026-27), the new tax regime for senior citizens does not provide a higher basic exemption limit based on age.
The same slab structure applies to senior citizens, super senior citizens and younger individual taxpayers, starting with a ₹4 lakh nil-rate slab.
A significant benefit can still arise through Section 87A, which offers a rebate of up to ₹60,000 for eligible resident individuals with taxable income up to ₹12 lakh, subject to the applicable conditions.
The ₹3 lakh basic exemption for senior citizens and ₹5 lakh exemption for super senior citizens are features of the old regime, not the new regime.
This guide covers the new-regime slabs, senior-citizen tax treatment, Section 87A, pension and interest income, and the key differences from the old regime.
Discover More About:👇
New Tax Regime for Senior Citizens
What Is the New Tax Regime for Senior Citizens?
For income-tax purposes, a senior citizen is generally an individual who is 60 years or more but below 80 years of age during the relevant financial year. A super senior citizen is generally an individual aged 80 years or more.
The distinction is important because the old tax regime provides different basic exemption limits based on age. Under the new regime, however, age does not create a separate slab structure.
The Income Tax Department’s AY 2026-27 tables show the same new-regime rates for individuals aged 60–79 and those aged 80 or above.
The new regime operates under Section 115BAC of the Income Tax Act. For individual taxpayers, it is the default regime, although eligible taxpayers can choose the old regime subject to the applicable rules for their income and filing situation.
This means a 65-year-old and a 40-year-old with the same taxable income generally face the same new-regime slab rates. Being a senior citizen does not itself reduce the rate or increase the nil-rate threshold.
You May Also Like To Read These Posts 👇
What Is a New Tax Regime? Complete Beginner’s Guide 2025-26
How to Save Tax in New Tax Regime – Legal Ways & Practical Tips
Tax on Rs 12 Lakh / Rs 15 Lakh / Rs 20 Lakh Income Under New Regime
Senior Citizen Tax Slab Under the New Regime for FY 2025-26
The new tax regime slabs for senior citizens for FY 2025-26 are the same as those applicable to other individuals.
| Taxable Income | New Tax Regime Rate |
|---|---|
| Up to ₹4 lakh | Nil |
| ₹4 lakh to ₹8 lakh | 5% |
| ₹8 lakh to ₹12 lakh | 10% |
| ₹12 lakh to ₹16 lakh | 15% |
| ₹16 lakh to ₹20 lakh | 20% |
| ₹20 lakh to ₹24 lakh | 25% |
| Above ₹24 lakh | 30% |
These rates apply progressively. For example, a senior citizen with ₹10 lakh of taxable income does not pay 10% on the entire ₹10 lakh.
The first ₹4 lakh falls in the nil slab, the next ₹4 lakh is taxed at 5%, and only the remaining ₹2 lakh is taxed at 10%.
A taxpayer aged 85 does not receive a separate lower rate under the new regime. The same slab structure applies to a super senior citizen.
New Tax Regime Slabs for Senior Citizens vs Old Regime
The biggest age-related difference appears when the new regime is compared with the old regime.
| Feature | Old Tax Regime | New Tax Regime |
|---|---|---|
| Basic exemption for age 60–79 | ₹3 lakh | ₹4 lakh |
| Basic exemption for age 80+ | ₹5 lakh | ₹4 lakh |
| Separate age-based slabs | Yes | No |
| Section 87A rebate | Up to ₹12,500, subject to conditions | Up to ₹60,000, subject to conditions |
| Standard deduction for salary/pension | ₹50,000 | ₹75,000 |
| Many Chapter VI-A deductions | Generally available | Generally restricted, subject to specified exceptions |
The old regime gives senior citizens and super senior citizens higher basic exemption thresholds. Under the new regime, the ₹4 lakh nil-rate slab applies irrespective of age.
For example, an eligible super senior citizen with ₹8 lakh of taxable income under the old regime has the first ₹5 lakh covered by the basic exemption, while the remaining ₹3 lakh falls into the applicable old-regime slab.
It is therefore incorrect to describe the entire ₹8 lakh as tax-free.
The choice between the regimes also depends on deductions and the taxpayer’s income mix. A senior citizen with substantial eligible deductions under the old regime may have a different result from someone whose income mainly consists of pension and interest.
Tax Exemption for Senior Citizens in the New Tax Regime
There is no separate age-based tax exemption under the new regime beyond the common ₹4 lakh nil-rate slab. A taxpayer does not receive an additional ₹1 lakh or ₹2 lakh exemption merely for being 60 or 80 years old.
The other major provision is Section 87A, which provides a rebate for eligible resident individuals.
For AY 2026-27, the rebate under the new regime can be up to ₹60,000 where taxable income does not exceed ₹12 lakh, subject to the applicable rules.
For example, if a resident senior citizen has ₹10 lakh of taxable income consisting entirely of normal-rate income, the slab tax is ₹40,000. A qualifying Section 87A rebate can eliminate that tax liability because the rebate can cover up to ₹60,000.
The distinction between gross income and taxable income is important. A pensioner may have gross pension income above ₹12 lakh but arrive at taxable income of ₹12 lakh or less after an applicable standard deduction.
Eligibility still depends on the full rebate conditions and the nature of the income.
For salaried taxpayers and pensioners, the standard deduction under the new regime is ₹75,000. This can reduce taxable income before the slab rates are applied.
Special-rate income requires separate consideration. The Section 87A rebate should not be treated as a blanket credit against every type of tax, particularly where income is taxed under special provisions.
How Much Tax Does a Senior Citizen Pay Under the New Regime?
Example 1: Senior Citizen With ₹10 Lakh Taxable Income
Suppose a 65-year-old resident senior citizen has ₹10 lakh of taxable income under the new regime and the entire amount is subject to normal slab rates.
The calculation is:
- Up to ₹4 lakh: Nil
- ₹4 lakh to ₹8 lakh: ₹4 lakh × 5% = ₹20,000
- ₹8 lakh to ₹10 lakh: ₹2 lakh × 10% = ₹20,000
- Tax before rebate: ₹40,000
Because the taxable income is within the ₹12 lakh Section 87A threshold, an eligible resident taxpayer can receive a rebate of up to ₹60,000. In this example, the rebate is sufficient to reduce the ₹40,000 income-tax liability to nil.
Example 2: Senior Citizen With ₹15 Lakh Taxable Income
Now consider a 70-year-old resident senior citizen with ₹15 lakh of taxable income, again assuming the entire amount is taxed at normal slab rates.
The calculation is:
- Up to ₹4 lakh: Nil
- ₹4 lakh to ₹8 lakh: ₹20,000
- ₹8 lakh to ₹12 lakh: ₹40,000
- ₹12 lakh to ₹15 lakh: ₹3 lakh × 15% = ₹45,000
- Tax before cess: ₹1,05,000
- Health and Education Cess at 4%: ₹4,200
- Total: ₹1,09,200
The Section 87A rebate does not apply because taxable income exceeds ₹12 lakh. The example assumes no surcharge and no income taxed at a special rate.
The Income Tax Department specifies a 4% Health and Education Cess on income tax and surcharge, where applicable.
Pension, Interest and Other Income Under the New Regime
A senior citizen’s tax calculation depends on the source of income as well as the total amount.
Pension received from a former employer is generally taxable as salary. A taxpayer receiving eligible pension income can claim the applicable ₹75,000 standard deduction under the new regime.
Family pension is treated differently from a regular pension. It is generally taxable under the head “Income from Other Sources” and the applicable deduction under Section 57(iia) can be available, subject to the prescribed limit and conditions.
For the new regime, the deduction is capped at one-third of family pension or ₹25,000, whichever is lower.
Bank and fixed-deposit interest is generally included in taxable income and can be taxed at the applicable slab rates.
The old regime provides the senior-citizen-specific Section 80TTB deduction for eligible interest income, but that deduction is not available under the new regime.
Rental income is calculated under the applicable house-property rules.
The new regime can still allow specified deductions for a let-out property, including the applicable deduction for interest on borrowed capital under Section 24(b), subject to the rules governing that property.
Capital gains can be subject to separate tax rates. For example, listed-equity gains covered by Sections 111A and 112A are not simply added to normal slab-rate income and taxed in exactly the same way.
The treatment of special-rate income should therefore be considered separately when assessing the final tax liability.
Senior Citizen vs Super Senior Citizen Under the New Regime
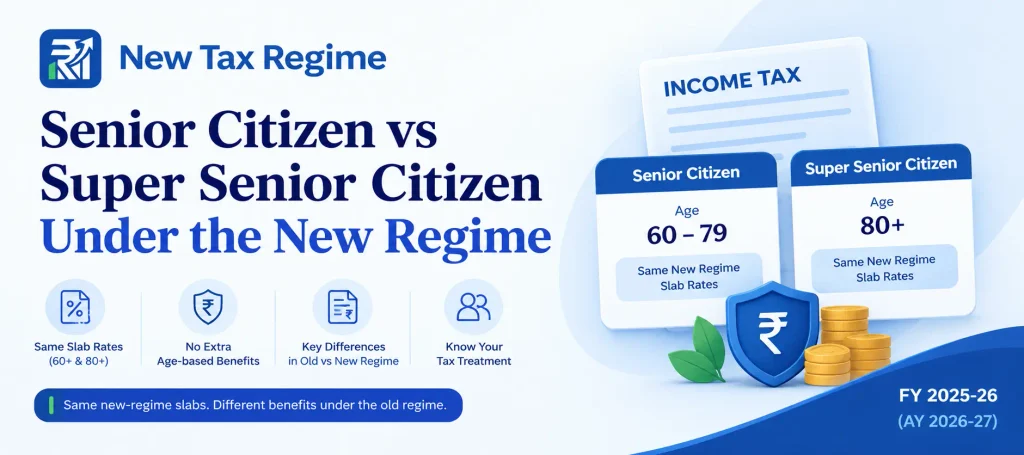
An individual aged 80 or above does not receive a different new-regime slab structure merely because they qualify as a super senior citizen.
For FY 2025-26, the new-regime table for taxpayers aged 80 or above still starts at ₹4 lakh and follows the same 5%, 10%, 15%, 20%, 25% and 30% progression shown for other individuals.
The important age-based difference is under the old regime. A senior citizen aged 60–79 has a ₹3 lakh basic exemption, while a super senior citizen aged 80 or above has a ₹5 lakh basic exemption.
Those higher age-based thresholds are not carried into the new regime.
Therefore, a person turning 80 does not automatically move into a more favorable new-regime slab. The taxpayer’s age changes the old-regime treatment, but not the new-regime slab rates.
Key Points to Check Before Choosing the New Regime
The regime choice should be based on the taxpayer’s actual income and eligible deductions rather than age alone.
First, calculate total taxable income after applicable deductions. A senior citizen receiving pension may have a different result from someone whose income is primarily interest, rent or capital gains.
Second, consider the value of deductions that are available under the old regime but generally unavailable under the new regime. Examples include Section 80C, Section 80D and Section 80TTB, subject to their individual conditions.
Third, account for the ₹75,000 standard deduction where salary or eligible pension income is involved. This can materially change the taxable income figure used for the slab calculation.
Fourth, check Section 87A separately. An eligible resident individual with taxable income within the ₹12 lakh threshold may receive a rebate of up to ₹60,000, but special-rate income should not be treated as automatically covered by the rebate.
Finally, compare the tax result under both regimes when the taxpayer has substantial deductions, multiple income sources or capital gains. The same gross income can produce different taxable-income figures under the two regimes.
You May Also Like To Read These Posts 👇
Hidden Costs & Disadvantages of New Tax Regime Nobody Tells You
Can You Switch Between Old and New Tax Regime Every Year?
HUF Tax Slab Under New Regime for FY 2025-26 (AY 2026-27)
Key Takeaways
- The new regime does not provide a separate tax slab for senior citizens or super senior citizens.
- For FY 2025-26, the new regime starts with a ₹4 lakh nil-rate slab for individuals regardless of age.
- The old regime provides a ₹3 lakh basic exemption for senior citizens and ₹5 lakh for super senior citizens.
- Eligible resident individuals can receive a Section 87A rebate of up to ₹60,000 when taxable income does not exceed ₹12 lakh, subject to applicable conditions.
- Eligible salary and pension income can qualify for a ₹75,000 standard deduction under the new regime.
- Interest, pension, rental income and capital gains can have different tax treatment, so the source of income matters when calculating final tax.
Frequently Asked Questions
Is there a separate tax slab for senior citizens under the new tax regime?
No. The new regime under Section 115BAC does not provide a separate slab based on whether an individual is a senior citizen or super senior citizen.
The same new-regime rates apply across these age groups.
What is the tax exemption limit for senior citizens under the new tax regime?
The new regime provides a ₹4 lakh nil-rate slab for individuals, including senior citizens.
The old regime’s higher ₹3 lakh and ₹5 lakh age-based basic exemption limits do not apply under the new regime.
Does Section 87A rebate apply to senior citizens?
Yes. An eligible resident senior citizen can claim the new-regime Section 87A rebate of up to ₹60,000 when the applicable taxable-income condition is satisfied. The rebate should not be treated as covering tax arising from every type of special-rate income.
Is the new tax regime different for super senior citizens?
No. Being 80 years or older does not create a separate new-regime slab.
The age-based ₹5 lakh basic exemption belongs to the old regime, while the new regime uses the common ₹4 lakh nil-rate slab.
Is pension income taxable under the new tax regime?
Yes. Regular pension from a former employer is generally taxable as salary income. Eligible pensioners can claim the ₹75,000 standard deduction under the new regime, while family pension is subject to different rules and may qualify for the deduction under Section 57(iia).

2 Comments
Pingback: HUF Tax Slab Under New Tax Regime FY 2025-26
Pingback: Tax on 15 Lakh Income in New Regime FY 2026-27