
Tax can still be legally reduced under the new tax regime for FY 2025-26 (AY 2026-27), although the available deductions are more limited than under the old regime.
For eligible taxpayers, the main benefits include the ₹75,000 standard deduction, Section 87A rebate of up to ₹60,000, and eligible employer contributions to NPS under Section 80CCD(2).
The key to understanding how to save tax in new tax regime is knowing which benefits remain available and avoiding deductions that the new regime does not permit.
Discover More About:👇
How to Save Tax in New Tax Regime
Can You Save Tax Under the New Tax Regime?
Yes. The new regime under Section 115BAC still provides specific deductions and rebates, but it does not allow most of the traditional tax-saving deductions associated with the old regime.
A deduction reduces taxable income before tax is calculated. A rebate, such as the one under Section 87A, reduces the income-tax payable after the tax has been calculated.
For FY 2025-26, the most relevant tax-saving provisions for many salaried taxpayers are the ₹75,000 standard deduction, eligible employer NPS contributions under Section 80CCD(2), and the Section 87A rebate for qualifying resident individuals.
By contrast, deductions such as Section 80C and Section 80D, along with the usual HRA exemption, are generally not available when the new regime is used.
Use the ₹75,000 Standard Deduction to Reduce Taxable Salary
The standard deduction is one of the simplest tax benefits available to salaried taxpayers and pensioners under the new regime.
For FY 2025-26, the standard deduction available against eligible salary or pension income is ₹75,000. This deduction is available automatically and does not require any bills or proof of expenses.
How the Standard Deduction Works
The deduction reduces taxable salary rather than providing a direct ₹75,000 reduction in tax.
For example, if an eligible taxpayer has salary income of ₹15 lakh, the standard deduction can reduce the salary considered for tax purposes by ₹75,000, subject to the applicable rules.
The calculation is therefore:
₹15,00,000 salary − ₹75,000 standard deduction = ₹14,25,000
The taxpayer does not need to make a separate ₹75,000 investment to claim this deduction.
Standard Deduction for Pensioners
Eligible pension income is also covered by the standard deduction rules applicable to salary income. This should not be confused with the separate deduction available for certain family-pension recipients.
The distinction matters because family pension is treated differently from pension received from a former employer.
Check Whether You Qualify for the Section 87A Rebate
The Section 87A rebate can be more valuable than a normal deduction for taxpayers who fall within the relevant income limit.
For FY 2025-26, the new-regime rebate can be up to ₹60,000 where the eligible resident individual’s taxable income does not exceed ₹12 lakh.
The Income Tax Department confirms the ₹12 lakh threshold and ₹60,000 maximum rebate for AY 2026-27.
Who Can Claim the Rebate?
The benefit is available to qualifying resident individuals under the new regime. It is not a general deduction that can simply be subtracted from income.
The rebate is applied against income-tax payable, subject to the statutory conditions.
Income taxed at special rates, such as certain capital gains and lottery income, requires separate consideration.
For this reason, a taxpayer should not assume that having total income around ₹12 lakh automatically means that every component of income becomes tax-free.
Marginal Relief Above ₹12 Lakh
The new regime also provides marginal relief in specified circumstances when taxable income is slightly above the ₹12 lakh threshold.
The purpose is to prevent a small increase in income from producing an unusually large increase in tax because of the rebate threshold. The exact calculation depends on the taxpayer’s taxable income and the tax otherwise payable.
For accurate tax planning, marginal relief should therefore be calculated rather than estimated from gross salary alone.
Use Employer NPS Contribution Under Section 80CCD(2)
An employer’s contribution to an eligible NPS account can provide one of the most useful deductions under the new regime.
Under Section 80CCD(2), the employer’s contribution can be deducted subject to the applicable limit.
For the new regime, the limit is 14% of salary (basic plus dearness allowance) for both government and private-sector employees.
How Employer NPS Reduces Taxable Income
Suppose the relevant salary for the NPS calculation is ₹10 lakh and the employer contributes ₹1.40 lakh to NPS.
If the contribution satisfies the applicable conditions and remains within the permitted limit, the ₹1.40 lakh can qualify for deduction under Section 80CCD(2).
The benefit is different from an employee’s own NPS contribution. The new regime does not generally allow an employee to claim the familiar Section 80CCD(1B) deduction for their own additional NPS contribution.
Basic Salary Is Not the Same as CTC
A common mistake is to calculate the 14% limit using total CTC.
The relevant salary definition for Section 80CCD(2) is based on specified salary components, including basic salary and qualifying dearness allowance where applicable. It is not simply the employee’s entire CTC.
Therefore, an employee should check the salary structure and employer payroll records before estimating the deduction.
Employer NPS and the ₹7.5 Lakh Perquisite Rule
The tax treatment of employer contributions also needs to be considered alongside the rules covering aggregate employer contributions to specified retirement funds.
Where the combined employer contribution to NPS, recognised provident fund and approved superannuation fund exceeds the prescribed ₹7.5 lakh threshold, the excess can become taxable as a perquisite, subject to the applicable rules.
This makes the overall compensation structure relevant when employer retirement contributions are substantial.
Know Which Popular Tax Deductions Are Not Available
One of the easiest ways to make a wrong tax calculation is to carry old-regime deductions into the new regime.
| Tax-saving option | New Regime FY 2025-26 | What it means |
|---|---|---|
| Section 80C | Generally not available | Investments such as PPF, ELSS and eligible insurance premiums generally do not create an 80C deduction |
| Section 80D | Generally not available | Health-insurance deductions under 80D generally cannot be claimed |
| HRA exemption | Generally not available | The usual HRA exemption does not apply under the new regime |
| Own NPS contribution under 80CCD(1B) | Generally not available | The additional ₹50,000 NPS deduction is an old-regime benefit |
| Self-occupied home-loan interest under Section 24(b) | Generally not available | The usual deduction for interest on a self-occupied property is not available |
| Let-out property interest under Section 24(b) | Can be available subject to conditions | The treatment of house-property loss is restricted under the new regime |
| Standard deduction | Available up to ₹75,000 | Reduces eligible salary or pension income |
| Section 87A rebate | Up to ₹60,000 | Available to qualifying resident individuals subject to the income and other conditions |
| Employer NPS under 80CCD(2) | Up to 14% of salary | One of the major deductions retained under the new regime |
The exact treatment of individual income or deductions can depend on the nature of the income and the conditions attached to the provision.
How to Reduce Tax in New Regime Through Salary and Income Planning
Once the standard deduction and rebate have been considered, tax planning becomes more dependent on the taxpayer’s salary structure and income composition.
Review Employer NPS
If an employer provides an NPS contribution as part of the compensation structure, check whether the contribution can be increased within the applicable limit.
This can reduce taxable income while also building retirement savings.
However, increasing the NPS component can change the amount received as cash salary, so the overall compensation should be compared rather than looking at tax savings alone.
Check Taxable Perquisites
Not every benefit provided by an employer is automatically taxable in the same way.
Some allowances, reimbursements or employer-provided benefits may receive specific tax treatment when their statutory conditions are met.
The correct approach is to check the nature of the benefit rather than assuming that every salary component is either fully taxable or fully exempt.
Separate Normal Income From Special-Rate Income
Tax planning becomes more complicated when salary or business income is combined with capital gains, lottery income or other income taxed at special rates.
A Section 87A rebate should not be treated as a blanket reduction of tax on every type of income.
The tax calculation should identify income taxable under normal slab rates separately from income subject to special rates.
Compare the Two Tax Regimes
The new regime is not automatically better for every taxpayer.
Someone with substantial old-regime deductions may need to calculate both options before making the final choice.
The comparison should use actual taxable income and eligible deductions rather than a fixed “deductions above X amount” rule.
Worked Example: How Employer NPS Can Reduce Tax
Consider a salaried taxpayer with the following income for FY 2025-26:
- Salary income: ₹15,00,000
- Eligible employer NPS contribution: ₹1,40,000
- Standard deduction: ₹75,000
Step 1: Apply the Standard Deduction
₹15,00,000 − ₹75,000 = ₹14,25,000
The salary income remaining for the tax calculation is therefore ₹14,25,000, before considering the eligible employer NPS deduction.
Step 2: Deduct Employer NPS Contribution
Assuming the entire ₹1,40,000 employer contribution qualifies under Section 80CCD(2):
₹14,25,000 − ₹1,40,000 = ₹12,85,000
The resulting taxable income for this simplified example is ₹12,85,000, ignoring other income, deductions or adjustments that may apply in an individual case.
Step 3: Calculate Tax Using the New-Regime Slabs
For FY 2025-26, the new regime has the following slab structure:
- Up to ₹4 lakh: Nil
- ₹4 lakh–₹8 lakh: 5%
- ₹8 lakh–₹12 lakh: 10%
- ₹12 lakh–₹16 lakh: 15%
For ₹12.85 lakh of taxable income, the tax before cess is:
- First ₹4 lakh: ₹0
- Next ₹4 lakh at 5%: ₹20,000
- Next ₹4 lakh at 10%: ₹40,000
- Remaining ₹85,000 at 15%: ₹12,750
Tax before cess = ₹72,750
Since the taxable income exceeds ₹12 lakh, the taxpayer in this simplified example does not receive the full Section 87A rebate.
Health and Education Cess at 4% would then be considered on the applicable income-tax amount.
What Does the NPS Contribution Save?
Without the employer NPS deduction, taxable income in this simplified example would be ₹14,25,000.
Tax before cess would then be:
- First ₹4 lakh: ₹0
- Next ₹4 lakh at 5%: ₹20,000
- Next ₹4 lakh at 10%: ₹40,000
- Remaining ₹2.25 lakh at 15%: ₹33,750
Tax before cess = ₹93,750
The difference in tax before cess is therefore:
₹93,750 − ₹72,750 = ₹21,000
After applying the 4% cess to the respective tax amounts, the saving is approximately ₹21,840.
This illustrates why the tax benefit of NPS should be calculated according to the slabs actually affected.
A deduction does not automatically produce a tax saving equal to the deduction multiplied by the highest tax rate.
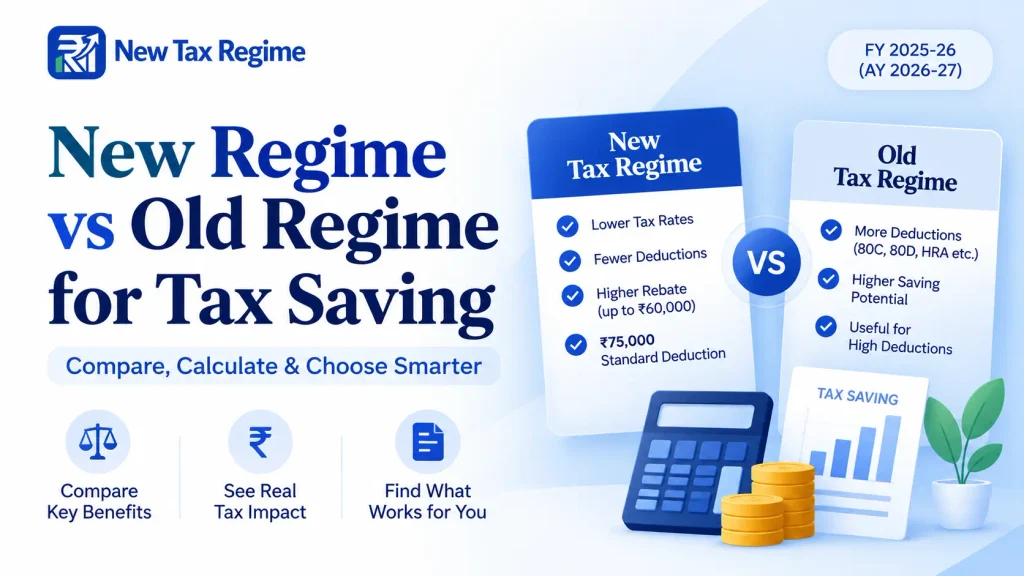
New Regime vs Old Regime for Tax Saving
The better regime depends on the taxpayer’s actual income, deductions, exemptions and salary structure.
| Factor | New Regime | Old Regime |
|---|---|---|
| Standard deduction | ₹75,000 | ₹50,000 |
| Section 80C | Generally unavailable | Up to ₹1.5 lakh, subject to conditions |
| Section 80D | Generally unavailable | Available subject to applicable limits |
| HRA exemption | Generally unavailable | Available subject to conditions |
| Self-occupied home-loan interest | Generally unavailable | Up to ₹2 lakh, subject to conditions |
| Employer NPS under 80CCD(2) | Up to 14% of salary | Different limits can apply depending on employer category |
The new regime often works well for taxpayers who do not have large deductions. The old regime can become more attractive when a taxpayer has substantial eligible deductions and exemptions.
There is no single deduction amount that determines the better regime for everyone. A taxpayer should calculate the tax payable under both regimes using their actual income and eligible benefits.
Practical Checklist for Saving Tax Under the New Regime
Before finalising your tax calculation for FY 2025-26:
- Calculate your total income from salary, business, investments and other sources.
- Apply the ₹75,000 standard deduction where eligible.
- Check whether you qualify for the Section 87A rebate.
- Identify any income that is taxed at a special rate, such as specified capital gains.
- Check whether your employer provides an eligible Section 80CCD(2) NPS contribution.
- Confirm the contribution limit using the correct definition of salary.
- Do not automatically claim 80C, 80D, HRA or self-occupied home-loan interest under the new regime.
- If you have substantial deductions, calculate the liability under the old regime as well.
- Verify the final calculation against the applicable income-tax rules before filing the return.
Key Takeaways
- The ₹75,000 standard deduction is one of the simplest tax benefits available to eligible salaried taxpayers and pensioners under the FY 2025-26 new regime.
- The Section 87A rebate can be up to ₹60,000 for qualifying resident individuals whose taxable income falls within the prescribed limit.
- Employer NPS contributions under Section 80CCD(2) can provide an additional deduction, subject to the applicable 14% salary limit under the new regime.
- Popular deductions such as 80C and 80D, the usual HRA exemption and self-occupied home-loan interest are generally not available under the new regime.
- Employer NPS should be evaluated as part of the complete salary structure because it can change the amount of cash salary received.
- The old and new regimes should be compared using the taxpayer’s actual income and eligible deductions, rather than relying on a fixed break-even figure.
Frequently Asked Questions
Can I save tax under the new tax regime?
Yes. The new regime still provides specific tax benefits, including the ₹75,000 standard deduction, the eligible Section 87A rebate, and employer NPS deduction under Section 80CCD(2).
The available benefits are narrower than those under the old regime.
What is the best way to reduce tax in the new regime?
For many salaried taxpayers, checking the standard deduction and making full use of an eligible employer NPS contribution are practical starting points.
Taxpayers should also check Section 87A eligibility and compare the final liability under both regimes where appropriate.
Is Section 80C available in the new tax regime?
Generally, no. Common Section 80C investments and payments such as eligible PPF, ELSS and insurance-related contributions do not provide the normal 80C deduction under the new regime.
Can I claim an NPS deduction in the new tax regime?
An eligible employer contribution under Section 80CCD(2) can be deducted subject to the applicable limit.
An individual’s own NPS contribution under Section 80CCD(1) or the additional 80CCD(1B) deduction is generally not available under the new regime.
How does the ₹60,000 Section 87A rebate work?
For FY 2025-26, a qualifying resident individual with taxable income within ₹12 lakh can receive a rebate of up to ₹60,000, subject to the statutory conditions.
The rebate is applied against tax payable and should not be treated as a deduction from income. Income taxed at special rates requires separate consideration.
Conclusion
The new tax regime has fewer deductions than the old regime, but taxpayers can still legally reduce their tax liability through provisions that remain available.
The ₹75,000 standard deduction, Section 87A rebate, and eligible employer NPS contribution under Section 80CCD(2) are among the most important benefits to check for FY 2025-26.
The safest approach is to calculate taxable income carefully, separate normal-rate and special-rate income, use only deductions actually permitted under the new regime, and compare the final liability with the old regime where relevant.
Disclaimer: This content is provided for general informational purposes and should not be treated as professional tax, legal, or financial advice.
Individual tax liability can vary based on income type, taxpayer status, salary structure and applicable rules.
