
For FY 2025-26 (AY 2026-27), a meal card is not tax-exempt under the new tax regime. The paid-voucher exemption that applies to eligible meal cards under the old regime is specifically excluded for employees taxed under the new regime.
Employer-provided food coupons and meal vouchers are therefore treated as taxable perquisites under the applicable rules.
Conveyance allowance follows a different path. An allowance granted to meet conveyance expenditure incurred in the performance of official employment.
Duties can still qualify for exemption under the new regime, provided the prescribed conditions are satisfied. A fixed allowance for ordinary home-to-office commuting does not receive the same treatment.
This guide explains how a meal card works under the new tax regime, how food coupons and meal coupons are treated, when conveyance allowance remains eligible for exemption, and what employees should verify in Form 16 before filing their ITR.
Discover More About:👇
Meal Card & Conveyance in New Tax Regime
Is a Meal Card Tax-Free Under the New Tax Regime?
For FY 2025-26, the old paid-voucher exemption for meals does not apply to an employee who has opted for the new tax regime.
Rule 3 governs the valuation of meal-voucher perquisites and specifically excludes this exemption for taxpayers covered by the new-regime provisions.
Under the old regime, eligible employer-provided paid vouchers that are non-transferable and usable only at eating joints can qualify for the prescribed exemption of ₹50 per meal, subject to the applicable conditions.
That specific benefit does not carry over to the new regime.
The name of the benefit also does not decide its tax treatment. A payslip may contain a separate line called “meal card”, “food coupon” or “meal allowance”, but the tax outcome depends on the nature of the benefit and the rules applicable to the employee’s chosen regime.
For this reason, employees should look at how the employer has treated the benefit for TDS and Form 16 rather than assuming that a separately displayed salary component is automatically exempt.
Food Coupon in New Tax Regime: What Employees Should Know
A food coupon in new tax regime does not receive the old-regime paid-voucher exemption for FY 2025-26.
This applies to employer-provided meal vouchers and similar qualifying instruments covered by the perquisite rules.
A useful distinction is between a non-cash food benefit and a cash allowance.
A meal card or food voucher provided by an employer is a non-cash employee benefit.
A cash food allowance, on the other hand, is simply an amount paid as part of salary. Calling the latter a “food allowance” does not by itself create an exemption.
Suppose an employer credits a fixed food allowance directly to an employee’s bank account every month.
That amount is generally treated as part of salary rather than receiving the special paid-voucher treatment available under the old rules.
The same principle applies when reviewing a salary breakup. An employer can show a benefit separately for payroll purposes while still including its taxable value when calculating salary income.
Meal Coupon in New Tax Regime vs Old Regime
The meal coupon in new tax regime treatment is different from the treatment under the old regime.
The key distinction is the availability of the specific paid-voucher exemption:
| Benefit | Old Regime | New Regime, FY 2025-26 | Main Point |
|---|---|---|---|
| Eligible meal voucher | Limited exemption may apply | Exemption not available | Conditions under Rule 3 matter |
| Food coupon | Limited exemption may apply | Taxable under applicable perquisite rules | Employer-provided benefit |
| Cash food allowance | Generally taxable | Generally taxable | Cash payment does not become exempt merely because of its label |
| Official-duty conveyance allowance | Eligible amount can qualify subject to conditions | Eligible amount can qualify subject to conditions | Must relate to prescribed official-duty expenditure |
| Ordinary home-to-office transport allowance | Generally taxable unless a specific exemption applies | Generally taxable for ordinary employees | Separate rules apply to eligible employees with disabilities |
The old regime therefore offers a specific benefit for qualifying meal vouchers that is not available under the new regime for FY 2025-26.
The comparison also shows why employees should not treat every salary component in the same way. Meal vouchers, cash allowances and official-duty reimbursements can fall under different provisions.
Conveyance Allowance in New Tax Regime: Is It Exempt?
Conveyance allowance in new tax regime can receive favourable treatment when it falls within the prescribed category of allowance for expenditure incurred while performing employment duties.
Rule 2BB specifically includes an allowance granted to meet expenditure incurred on conveyance in the performance of duties of an office or employment, subject to the stated conditions.
The rule also covers certain travel-on-tour and transfer-related allowances.This is different from a general commuting allowance.
For example, travel from an employee’s office to a client’s premises for an official assignment can fall within the official-duty category.
Daily travel from the employee’s home to the normal workplace is not automatically treated in the same way.
The important point is that the tax treatment depends on why the allowance is paid and what expense it is intended to meet. A salary structure containing a line called “conveyance allowance” does not, by itself, establish that the amount is exempt.
Official Travel vs Regular Commuting
Consider two employees receiving ₹3,000 a month as a conveyance-related component.
Employee A uses the allowance for travel between the office and client locations while performing official duties.
Employee B receives the same amount as a fixed commuting allowance for travelling between home and the regular workplace.
The amounts have the same label, but their tax treatment can differ because the underlying purpose is different.
For eligible official-duty expenditure, the exemption is subject to the prescribed conditions and the amount actually incurred. Employees should therefore retain appropriate supporting records where relevant.
Conveyance Allowance Exemption in New Tax Regime: Exceptions and Conditions
The conveyance allowance exemption in new tax regime is not a blanket exemption for every transport-related payment.
Under Rule 2BB, specified allowances relating to travel on tour, transfer and conveyance in the performance of employment duties are among the allowances that can remain eligible under the new regime, subject to their conditions.
Home-to-office transport
For an ordinary employee, a fixed transport allowance for daily commuting does not generally receive the official-duty conveyance treatment.
There is, however, a separate provision for transport allowance granted to an employee who is blind, deaf and dumb, or orthopaedically handicapped with disability of the lower extremities, for commuting between residence and place of duty.
Rule 2BB specifies an exemption of ₹3,200 per month for this category, subject to the applicable conditions.
This should not be confused with the general conveyance allowance available for official travel.
What employees should check
Before treating a conveyance component as exempt, check:
- whether it is connected with official employment duties;
- whether it falls within a prescribed category under Rule 2BB;
- whether the employer has treated it as exempt in payroll;
- whether the required conditions have been satisfied; and
- whether the amount shown in Form 16 agrees with the salary records.
The safest approach is to assess the nature of the payment, not merely its name.
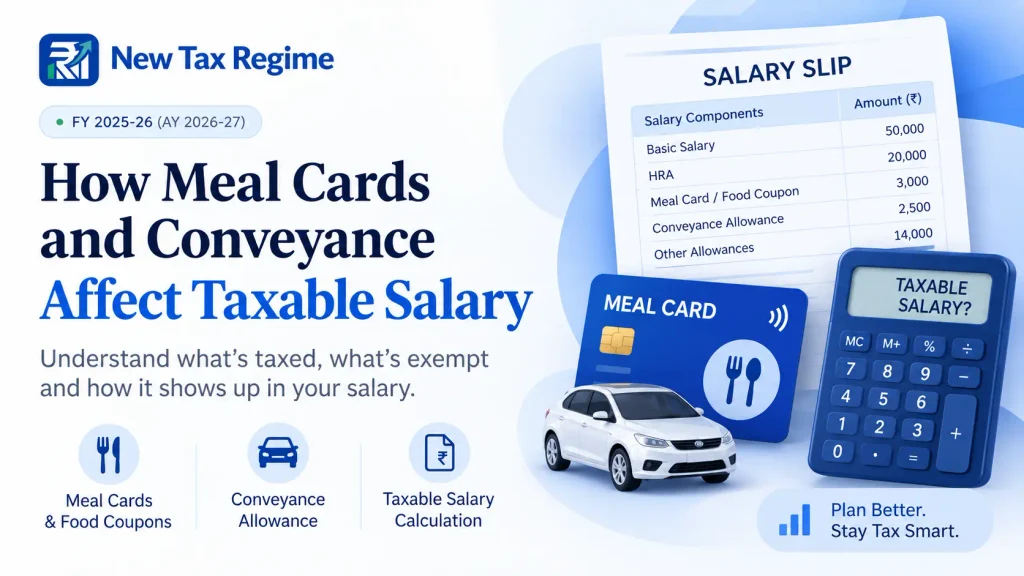
How Meal Cards and Conveyance Affect Taxable Salary
Consider a hypothetical employee, Priya, whose salary package contains the following components for FY 2025-26:
| Salary Component | Annual Amount | New-Regime Treatment |
|---|---|---|
| Basic salary | ₹6,00,000 | Taxable |
| HRA | ₹2,40,000 | Generally taxable under new regime |
| Employer meal-card benefit | ₹26,400 | Taxable under applicable perquisite rules |
| Fixed conveyance component | ₹19,200 | Generally taxable if it is ordinary fixed commuting allowance |
| Other allowances | ₹3,14,400 | Tax treatment depends on the nature of each component |
| Illustrative salary total | ₹12,00,000 | Before applicable salary deduction |
The example is deliberately simplified. A real salary calculation should not assume that every allowance is automatically taxable or exempt merely from its name.
If the conveyance amount represents a qualifying official-duty allowance under Rule 2BB, its eligible portion can receive the prescribed exemption. If it is simply a fixed monthly amount for normal commuting, the official-duty exemption does not apply.
The same distinction matters for meal benefits. The old-regime paid-voucher exemption cannot simply be carried into the new regime for FY 2025-26.
After determining taxable salary, an eligible salaried taxpayer under the new regime can also consider the applicable standard deduction, which is separate from the treatment of meal cards and conveyance allowances.
How to Check Your Salary Slip Before Filing ITR
Step 1: Identify whether the benefit is cash or non-cash
Check whether the employer has paid money directly or provided a specific benefit.
A food allowance credited with salary is different from a meal voucher. Similarly, reimbursement of official travel expenses is different from a fixed monthly conveyance allowance.
Step 2: Check the employer’s tax treatment
Look at the taxable salary and perquisite details used by the employer for TDS.
A separate line on the payslip does not necessarily mean that the amount is exempt.
Step 3: Review Form 16
Compare the salary breakup with Form 16, particularly the salary and perquisite information reported by the employer.
If a meal benefit has been treated as taxable, the employee should not independently assume that it can be removed while preparing the ITR.
Step 4: Check the nature of conveyance payments
Ask whether the payment relates to:
- ordinary home-to-office commuting;
- official travel during employment duties;
- travel on tour or transfer; or
- another prescribed category.
This classification can materially affect the tax treatment.
Step 5: Keep supporting records
Where an exemption depends on expenditure incurred for official duties, retain appropriate records such as employer travel statements, bills, reimbursement records or other relevant documentation.
The exact documents required can depend on the employer’s internal process and the nature of the allowance.
Step 6: Reconcile the final figures
The taxable salary used in the ITR should be consistent with the information reported by the employer, after accounting for legitimate adjustments and deductions.
If there is a difference, identify the particular salary component responsible rather than changing the figure without understanding the reason.
Key Takeaways
- Meal-card and paid meal-voucher exemptions available under the old regime do not apply under the new regime for FY 2025-26.
- A food coupon or meal card should be assessed according to the applicable perquisite rules rather than the name used in the salary slip.
- Official-duty conveyance allowances can remain eligible for exemption under the new regime when they fall within the prescribed Rule 2BB categories and satisfy the applicable conditions.
- A fixed allowance for ordinary home-to-office commuting should not automatically be treated as exempt.
- Eligible employees with specified disabilities have a separate ₹3,200-per-month transport allowance exemption under Rule 2BB, subject to the applicable conditions.
- Employees should compare their salary slip, Form 16 and tax treatment before claiming any exemption in the ITR.
Frequently Asked Questions
Is a meal card exempt in the new tax regime?
For FY 2025-26, the specific paid-voucher exemption available under the old regime does not apply when the employee is taxed under the new regime.
The employer-provided meal benefit therefore needs to be considered under the applicable perquisite rules.
Is a food coupon taxable under the new tax regime?
Generally, yes. The special exemption for eligible paid meal vouchers is not available to an employee covered by the new-regime provisions for FY 2025-26.
Can employees claim meal coupon exemption under the new regime?
The ₹50-per-meal paid-voucher exemption available under the old rules cannot be claimed by an employee who has opted for the new regime for FY 2025-26.
Is conveyance allowance exempt under the new tax regime?
Certain conveyance allowances connected with official employment duties can qualify under the prescribed Rule 2BB provisions, subject to their conditions.
A general fixed allowance for ordinary commuting does not automatically qualify.
How should meal cards and conveyance allowance be treated while calculating taxable salary?
Meal-card benefits should be considered under the applicable perquisite rules for the chosen regime.
Conveyance payments should first be classified according to their purpose and the relevant Rule 2BB category before determining whether any exemption is available.
Disclaimer: This article is intended for general informational purposes and should not be treated as professional tax or financial advice.
Individual tax treatment can vary depending on the nature of the income, benefit, employment arrangement and applicable conditions.
